France’s Debt Crisis Pits Voters Against Investors as Bond Yields Surge
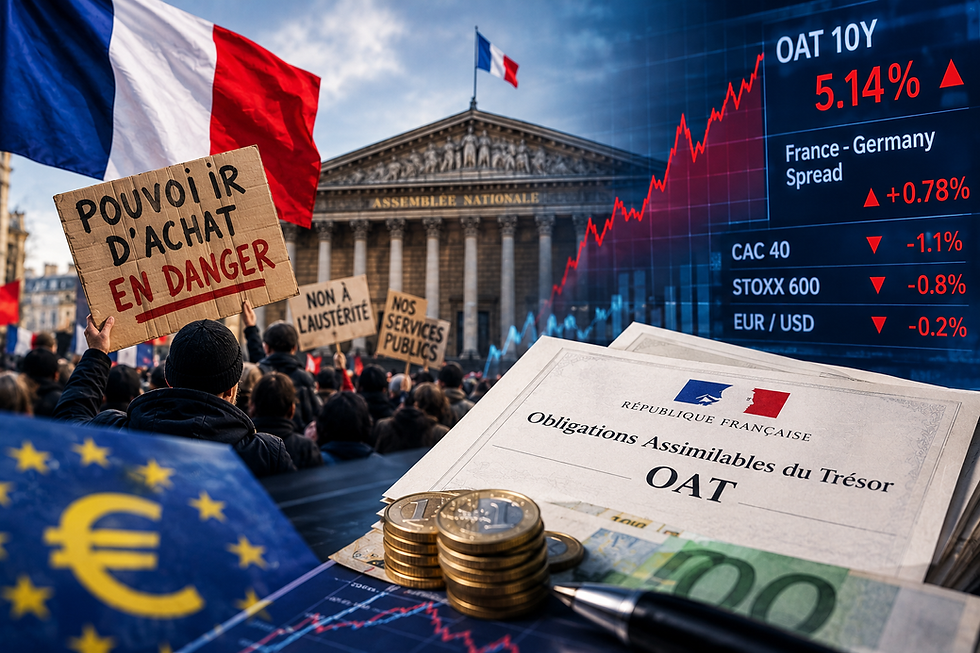
France is facing an increasingly difficult financial and political dilemma as rising public debt and borrowing costs collide with public resistance to spending cuts. Investors are demanding credible measures to reduce the country’s budget deficit, while voters remain concerned about the cost of living, public services and the impact of austerity.
The conflict is putting pressure on Prime Minister Sébastien Lecornu’s government as it attempts to secure support for its 2027 budget ahead of next year’s presidential election. For financial markets, the central question is whether France can restore confidence in its public finances without triggering further political instability.
According to RBC BlueBay Asset Management, the competing demands of voters and bond investors are creating a difficult environment for policymakers. Investors want evidence that France can control its debt burden, but the political cost of fiscal consolidation could make meaningful reform harder to implement.
The stakes extend beyond France. As one of the eurozone’s largest economies and a major sovereign bond issuer, France plays an important role in European financial markets. A prolonged deterioration in investor confidence could increase financing costs across the region and complicate the European Central Bank’s efforts to maintain stable financial conditions.
France’s Public Debt Reaches Record Levels
France’s public finances have deteriorated significantly in recent years. The country’s public debt reached approximately €3.596 trillion in the second quarter of 2026, equivalent to around 119% of gross domestic product, according to figures reported in October.
The government expects the debt-to-GDP ratio to reach approximately 119.3% by the end of 2026 and rise further to 121.7% in 2027 under its current projections.
France is also expected to record a budget deficit of approximately 5.4% of GDP in 2026, substantially above the European Union’s reference limit of 3%.
These figures illustrate the scale of the fiscal challenge. Persistent deficits mean the government continues to borrow to cover the gap between revenue and expenditure, while accumulated debt creates a growing obligation to pay interest and refinance maturing bonds.
Higher market interest rates are making that task more expensive. As new borrowing is issued and existing debt matures, the government must increasingly contend with financing conditions that are less favourable than those available during the period of exceptionally low interest rates.
The result is a difficult combination: France needs to reduce its deficit, but rising debt-servicing costs risk consuming resources that could otherwise support public investment and services.
Bond Investors Demand Fiscal Discipline
Investors in French government bonds, known as Obligations Assimilables du Trésor, or OATs, are increasingly focused on the government’s ability to stabilise public finances.
When investors become less confident about a government’s fiscal outlook, they may demand higher yields to compensate for the additional uncertainty. Bond prices fall as yields rise, increasing the cost at which the government can issue new debt or refinance existing obligations.
France experienced a sharp deterioration in its borrowing conditions during October. Its ten-year government bond yield rose above 5% and reached approximately 5.14% on October 22, its highest level since 2002. The yield spread over German government bonds also widened to levels last seen during the eurozone sovereign debt crisis.
The widening spread is particularly significant because German Bunds are widely used as a benchmark for eurozone sovereign debt. A larger difference indicates that investors are demanding a greater return to hold French debt rather than German securities.
The market is not necessarily predicting an imminent French default. Instead, the higher yields reflect concerns about fiscal sustainability, political uncertainty and the difficulty of passing a credible budget.
For the French Treasury, however, prolonged pressure could gradually increase the interest bill and make the task of reducing the deficit more difficult.
The Political Cost of Austerity
The government’s response is constrained by public opposition to spending reductions and other measures designed to improve the budget balance.
Prime Minister Sébastien Lecornu has proposed a 2027 budget centred on approximately €54 billion in savings. Measures under consideration include restrictions on public-sector spending, a freeze on public-sector wages and most pensions, alongside targeted tax measures.
The objective is to reduce the deficit from an expected 5.4% of GDP in 2026 to around 5% in 2027.
However, the proposals have encountered resistance from workers, students and other groups concerned about public services and household purchasing power. Previous governments have also struggled to maintain support for fiscal reforms, illustrating the political difficulty of implementing sustained spending restraint.
The government must therefore balance two competing pressures. Insufficient action risks further weakening investor confidence, while aggressive austerity measures could provoke demonstrations, undermine parliamentary support and increase the likelihood of policy reversals.
This tension is especially important ahead of the 2027 presidential election, when political parties have incentives to avoid measures that could alienate voters.
For investors, the problem is not simply whether France announces a savings programme. It is whether the government can implement the measures and sustain them long enough to change the country’s fiscal trajectory.
The 2027 Election Adds to Market Uncertainty
France’s approaching presidential election is adding another layer of uncertainty to the bond market.
Political competition is likely to intensify debate over taxation, public spending, pensions and the future direction of economic policy. Proposals that could materially alter the treatment of government debt or the relationship between France and European institutions may also influence investor sentiment.
Investors are particularly sensitive to the possibility that a future government could reverse fiscal measures or pursue policies that conflict with the expectations of bondholders.
The election could therefore affect borrowing costs well before voters go to the polls. Markets generally respond to expectations about future policies, not only to decisions that have already been implemented.
The challenge for France is to demonstrate that its fiscal commitments can survive political changes. A budget that depends on fragile parliamentary support may provide less reassurance than a plan backed by a durable political agreement.
Without greater clarity, uncertainty surrounding the election could continue to influence French bond yields, equity valuations and the euro.
Why the French-German Bond Spread Matters
The difference between French and German ten-year government bond yields is one of the most closely watched indicators of France’s sovereign risk premium.
When the spread widens, France faces a relative increase in borrowing costs compared with Germany. This can reflect concerns about the country’s debt trajectory, political stability or ability to implement reforms.
During October, the spread widened sharply as investors reassessed the risks surrounding France’s budget and election outlook. The movement also raised questions about potential spillovers to other heavily indebted eurozone economies.
A sustained increase in sovereign yields can affect banks, insurers, pension funds and other financial institutions holding government bonds. Changes in bond prices can influence portfolio valuations, while higher sovereign borrowing costs may eventually feed into financing conditions for businesses and households.
However, a wider spread does not automatically mean that a broader European debt crisis is inevitable. Its significance depends on how long the pressure persists, whether it spreads to other markets and how policymakers respond.
For European financial institutions, the key concern is whether the repricing remains limited to France or becomes a wider reassessment of sovereign risk across the eurozone.
Can the European Central Bank Intervene?
The European Central Bank is an important part of the discussion because sharp differences in government borrowing costs can complicate the transmission of monetary policy across the eurozone.
If financing conditions deteriorate significantly in one member state, businesses and households there may face different borrowing conditions from those in other countries, even when the ECB sets a common policy interest rate.
Investors are therefore debating whether a further widening of French-German bond spreads could eventually prompt a stronger response from European policymakers.
However, France cannot rely on the ECB to resolve its underlying fiscal problems. The central bank has repeatedly emphasised the importance of national governments maintaining sustainable public finances.
Any potential intervention would also depend on the circumstances and the applicable conditions. Monetary policy tools are not a substitute for a credible budget or a sustainable debt trajectory.
The distinction matters for markets: expectations of central bank support may temporarily influence bond prices, but lasting confidence depends heavily on France’s own fiscal and political decisions.
Moody’s Maintains France’s Rating but Keeps a Negative Outlook
France received temporary relief on October 23 when Moody’s maintained the country’s sovereign credit rating at Aa3. The agency nevertheless retained a negative outlook, reflecting continuing concerns about political instability and the government’s ability to reduce its deficit.
The decision helped ease immediate fears of a downgrade, but it did not eliminate the underlying fiscal risks.
Credit ratings influence how investors assess sovereign borrowers and can affect the investment policies of institutions that use rating thresholds. A downgrade may prompt some investors to reassess their holdings, although the market impact depends on the circumstances and expectations already reflected in bond prices.
Moody’s decision also highlighted the importance of the 2027 budget. Sustained fiscal consolidation, lower financing pressure and greater political stability would help support France’s credit standing.
The rating outlook therefore remains closely linked to the government’s ability to turn proposed savings into durable policy measures.
What the Debt Crisis Means for European Banks and Investors
France’s fiscal difficulties have implications for European financial markets beyond the government bond sector.
Banks hold sovereign debt as part of their liquidity and investment portfolios. Changes in bond prices can affect the valuation of these holdings, while uncertainty about economic growth may influence lending, credit demand and borrower risk.
Insurance companies and pension funds may also be affected by movements in government bond yields, depending on their portfolios and liabilities. Higher yields can improve prospective returns on new investments, but abrupt market movements can create valuation volatility.
For companies, higher sovereign borrowing costs can eventually contribute to tighter financing conditions. Governments facing rising interest payments may also have less flexibility to fund infrastructure, education, defence and other investment priorities.
International investors are consequently monitoring several indicators: French ten-year bond yields, the spread over German Bunds, progress on the budget, credit-rating decisions and political developments ahead of the election.
The interaction between these factors will help determine whether the current market pressure fades or becomes a more persistent challenge for European assets.
Outlook: France Must Reconcile Voter Priorities With Market Confidence
France’s debt challenge reflects a difficult structural problem rather than a single episode of market volatility. Persistent budget deficits, a high debt burden and rising interest costs are increasing the pressure on policymakers to act.
At the same time, the political environment limits the government’s room for manoeuvre. Spending cuts can provoke public resistance, while delaying fiscal adjustment risks increasing the cost of borrowing and narrowing future budget choices.
For investors, the central issue is whether France can establish a credible and politically sustainable path towards deficit reduction. The government’s ability to pass and implement the 2027 budget will be an important test.
For the wider eurozone, France’s experience is a reminder that sovereign debt sustainability depends not only on economic indicators but also on political institutions and the capacity to implement policy.
The immediate market pressure eased somewhat after Moody’s maintained its rating, but the negative outlook and elevated borrowing costs show that the underlying concerns remain.
Source: Financial Newswire


Kommentare